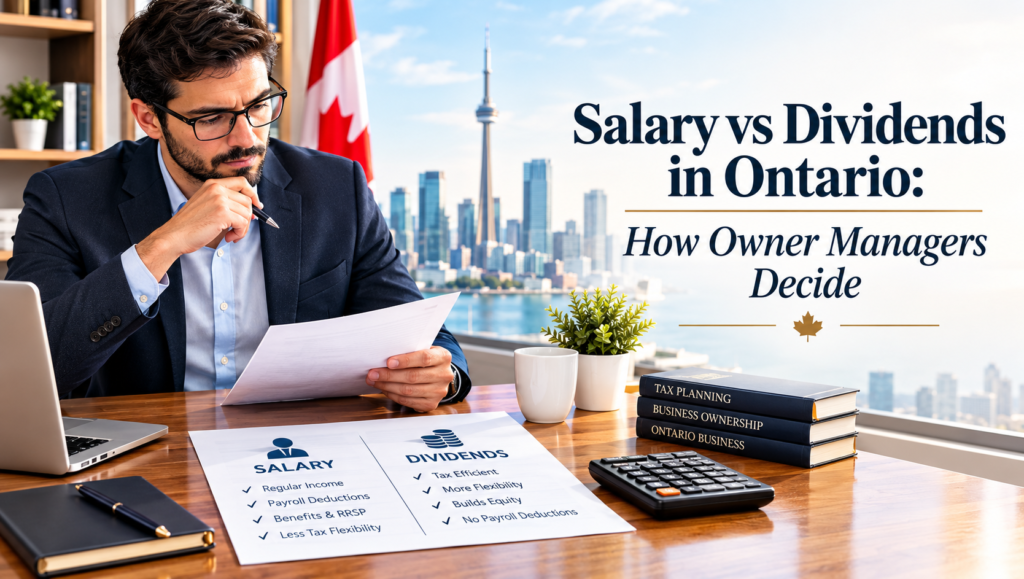
If you own an incorporated business, one question comes up sooner or later: how should you pay yourself? Should you receive a regular salary, take dividends from your corporation, or use a combination of both? The answer is not the same for every business owner. Salary vs Dividends Ontario decisions depend on your income, business profits, retirement plans, CPP contributions, RRSP goals and personal tax situations.
Salary or Dividends Ontario: What Is the Difference?
Salary and dividends are two different ways of taking money from an incorporated business.
When you receive a salary, your corporation treats the payment as an employment expense, subject to the applicable rules. Payroll deductions such as income tax and CPP generally apply. Salary also creates earned income that can contribute to the future RRSP contribution room.
A dividend, on the other hand, is generally paid for from the corporation’s after-tax profits. It is not a deductible expense for the corporation and does not create RRSP contribution room or CPP contributions. The personal tax treatment is different because Canada’s dividend tax system accounts for corporate tax already paid.
For many business owners, the real question is not simply salary or dividends from Ontario. It is whether a combination of the two makes more sense.
Salary vs Dividends Owner Manager Ontario: Which One Is Better?
There is no universal answer.
The right choice depends on what you need from your income today and what you are planning. An owner-manager who wants to build RRSP room may have different priorities from someone who wants to keep payroll costs lower or needs greater flexibility in taking money from the corporation.
Here is a simple comparison:
Factor | Salary | Dividends |
Corporate deduction | Generally deductible if requirements are met | Not deductible |
CPP | Generally applies | No CPP contribution |
RRSP room | Creates earned income for RRSP purposes | Does not create RRSP room |
Payroll administration | Required | No regular payroll deduction |
Paid from | Corporate income | After-tax corporate profits |
Flexibility | Often structured through payroll | Can provide flexibility depending on corporate profits |
Tax treatment | Employment income | Dividend income with applicable tax credit |
The best decision should consider both personal and corporate taxes, rather than looking only at the tax on your personal return.
Salary vs Dividends Ontario 2026: What Has Changed?
For 2026, Ontario business owners should pay attention to updated federal and provincial tax brackets as well as CPP limits. CRA’s 2026 payroll information shows a federal lowest tax rate of 14% and Ontario provincial tax brackets that have also been indexed.
CPP is another important consideration. In 2026, the CPP earnings ceiling is $74,600, with additional CPP contributions applying at higher earnings up to the second ceiling of $85,000.
That does not mean every owner-manager should automatically pay themselves $74,600 in salary. Your business profits, personal income, and long-term plans still matter.
How to Pay Yourself From Corporation Ontario
Before deciding how much to withdraw, start with a broader question: what do you actually need the money for?
For example, salary may be useful if you want to:
- Build RRSP contribution room
- Make regular personal income easier to document
- Build CPP benefits through contributions
- Create a predictable monthly income
- Reduce taxable corporate income where the salary qualifies as a deductible expense
Dividends may be attractive when:
- Your corporation has sufficient after-tax profits
- You do not need an additional RRSP room
- You want to avoid additional CPP contributions
- Your overall tax situation makes dividends suitable
- You want to access corporate profits outside regular payroll
However, simply taking money from the corporation without properly recording it can create tax problems. Payments and benefits involving shareholders need to be properly classified and documented. CRA specifically distinguishes between benefits received as an employee and benefits received because of share ownership.
Owner Manager Compensation Ontario: Why a Combination Can Work
Many incorporated business owners do not choose one method exclusively.
A salary-and-dividend combination can provide a balance between current income, retirement planning, and corporate cash flow. For example, an owner may use salary to support RRSP planning and CPP participation, while dividends may be considered for additional personal withdrawals when appropriate.
The important point is that the right mix can change.
A business may have a very profitable year followed by a slower year. Your personal income may also change because of mortgage, family expenses, investment plans, or retirement goals.
That is why owner manager compensation for Ontario planning should be reviewed regularly rather than treated as a one-time decision.
Owner Manager Tax Planning Ontario: Look Beyond the Tax Rate
Tax should certainly be part of the conversation, but it should not be the only factor.
Good owner manager for tax planning Ontario involves looking at your complete financial picture.
Consider:
- Your corporate profit
How much can the corporation realistically distribute without affecting working capital?
- Your personal income
Other income can change your marginal tax rate and affect the value of salary or dividends.
- Retirement plans
Salary can create RRSP contribution room, while dividends do not.
- CPP planning
Salary generally creates CPP contributions, while dividends do not. For 2026, the CPP limits have changed, so current figures should be used when making the calculation.
- Cash-flow needs
The best tax result on paper may not be the best decision if it leaves your corporation short of cash.
Salary vs Dividends CPP RRSP Ontario: The Long-Term Picture
The salary vs dividends CPP RRSP Ontario decision is often about more than saving tax this year.
Salary can help build RRSP room because RRSP limits are based on eligible earned income. RRSP contributions can then provide a tax deduction, subject to the applicable limits.
Salary also involves CPP contributions. Those contributions help determine eligibility for CPP benefits and can affect future benefits.
Dividends do not provide those same benefits, but they can still be useful as part of an overall compensation strategy.
The goal is therefore not to find a magic percentage. It is to choose a compensation strategy that fits your business, personal finances, and long-term goals.
Final Thoughts
There is no single formula for every business owner. The best Salary vs Dividends Ontario strategy depends on your corporation’s profits, personal tax position, CPP and RRSP goals, cash-flow requirements and future. A review each year can help you adjust your compensation instead of relying on an old rule of thumb.
If you are deciding how to structure your compensation, professional tax advice can help you compare the numbers before making the decision. For more information and professional accounting support, visit cpamg
Frequently Asked Questions
- Is salary or dividends better in Ontario?
Neither option is automatically better. Salary can provide RRSP room and CPP participation, while dividends may offer flexibility from after-tax corporate profits. Your individual circumstances determine the better approach.
- Can an Ontario business owner take both salary and dividends?
Yes. An owner-manager can potentially receive both salary and dividends, provided the payments are properly handled and documented.
- Does salary create RRSP contribution room?
Yes. Salary is generally considered earned income for RRSP purposes, subject to the applicable rules and limits. Dividends do not create RRSP contribution room.
- Do dividends require CPP contributions?
Dividends generally do not attract CPP contributions. Salary, on the other hand, is generally subject to CPP rules.
- Should I change my salary and dividend mix every year?
It can be worthwhile to review it annually. Changes in business profits, personal income, tax brackets, CPP limits, RRSP goals and cash-flow needs can all affect the appropriate compensation strategy.